The Difference Between Insurance Inspections and LOLER Thorough Examinations

Updated: Oct 24
When it comes to keeping lifting machinery and equipment safe and compliant, understanding the difference between insurance inspections and LOLER thorough examinations is crucial. Both play vital roles in maintaining safety standards, but they serve different purposes and follow distinct processes. I want to walk you through these differences clearly, so you know exactly what to expect and how to keep your equipment in top shape.
What Are Insurance Inspections?
Insurance inspections are primarily about risk management. When your business owns or manages lifting equipment, your insurance provider will often require regular inspections to assess the condition of your machinery. These inspections help the insurer understand the risk they are covering and determine your premiums accordingly.
Insurance inspections typically focus on:
Identifying visible damage or wear and tear
Checking if the equipment is being used according to manufacturer guidelines
Verifying that safety features are in place and functional
These inspections are usually less detailed than LOLER examinations but are essential for maintaining your insurance coverage. If your equipment fails an insurance inspection, it could lead to higher premiums or even refusal of coverage. Some engineering insurance policies also include the LOLER thorough examination itself, carried out by the insurer’s own engineer surveyor. That’s a different thing from a risk survey, and the table further down sets out how to tell them apart.
Practical Example
Imagine you have a forklift used daily in your warehouse. Your insurance company might send an inspector to check for obvious signs of damage, such as cracked forks or worn tyres. They want to ensure the forklift is safe enough to operate without posing a significant risk.

Understanding LOLER Thorough Examinations
LOLER stands for the Lifting Operations and Lifting Equipment Regulations 1998. These regulations require businesses to carry out thorough examinations of lifting equipment at regular intervals. Unlike insurance inspections, LOLER examinations are a legal requirement in the UK.
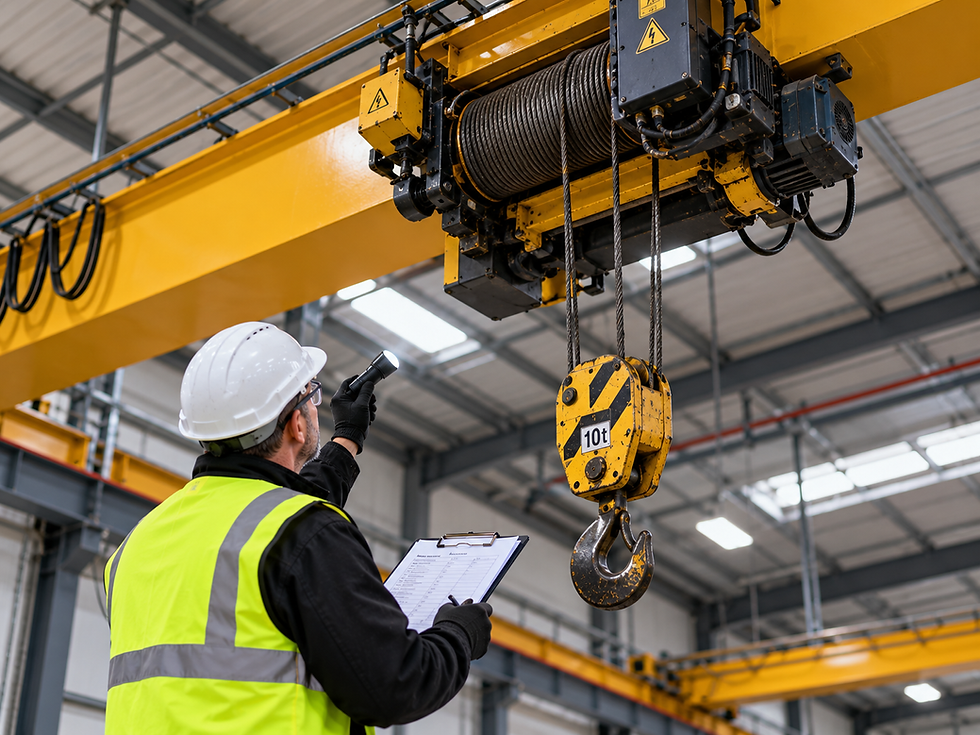
A LOLER thorough examination is a detailed inspection carried out by a competent person. It involves:
A comprehensive check of all parts of the lifting equipment
Load or functional tests, where the examiner judges they’re needed
Inspecting safety devices and control mechanisms
Reviewing maintenance records and previous examination reports
The goal is to ensure the equipment is safe to use and complies with legal standards. Any defect that is or could become a danger must be reported straight away. If it’s dangerous, the equipment can’t be used until it’s fixed. Other defects get a date to be put right by (LOLER Regulation 10).
Why LOLER Matters
LOLER examinations are about safety first. They help prevent accidents by catching issues that might not be visible during a simple insurance inspection. For businesses, this means protecting employees, avoiding costly downtime, and staying on the right side of the law.

Key Differences Between Insurance Surveys, Inspections and Independent LOLER Examinations
Now that we’ve covered what each inspection involves, let’s break down the main differences:
Insurer’s risk survey | Insurer’s LOLER examination | Independent LOLER examination | |
What it’s for | Helps the insurer decide whether to cover you, and on what terms | Meets your LOLER duty, arranged through your insurance policy | Meets your LOLER duty |
Counts as your LOLER thorough examination? | No | Yes, if the report says it’s a thorough examination under LOLER | Yes |
Who carries it out | The insurer’s surveyor or risk engineer | The insurer’s engineer surveyor | An independent competent person, such as PULO |
How often | When the insurer decides, often at the start of cover or at renewal | At LOLER intervals: at least every 6 months for equipment that lifts people and for accessories, 12 months for the rest | At LOLER intervals, or under a written examination scheme |
What you get | A risk report for the insurer, sometimes with recommendations for you | A report of thorough examination, often held on the insurer’s online portal | A report of thorough examination for each item, sent to you |
If you change insurer | It ends with the policy | Your examiner, schedule and report format all change | Nothing changes |
Price | Part of getting insured | Built into or added to your premium, and reviewed at renewal | A fixed quote that stays the same for all ongoing examinations |
Understanding these differences helps you plan your maintenance and inspection schedules effectively. You can’t rely on insurance inspections alone to meet legal requirements, and independent LOLER examinations provide a deeper level of safety assurance.
How to Prepare for Both Inspections
Preparation is key to passing both insurance inspections and LOLER thorough examinations without hassle. Here are some practical tips:
Keep Records Up to Date
Maintain detailed logs of all maintenance, repairs, and previous inspections. This documentation is crucial for both types of inspections.
Regular Internal Checks
Conduct your own routine checks between official inspections. Look for obvious signs of wear, leaks, or damage.
Train Your Staff
Ensure operators know how to use equipment safely and report any issues immediately.
Schedule Inspections Early
Don’t wait until the last minute. Book your LOLER examinations and insurance inspections well in advance to avoid downtime.
Work with Trusted Professionals
Choose inspection providers who understand your equipment and business needs. For example, PULO Compliance aims to be the go-to specialist for machinery inspections across the Midlands and wider areas, ensuring businesses keep their equipment safe and compliant without hassle. If you are thinking of switching to us for all your inspections then check out our simple guide to switching LOLER inspection companies.
Why Both Inspections Are Essential for Your Business
You might wonder if you can skip one type of inspection to save time or money. The truth is, both insurance inspections and LOLER thorough examinations serve different but complementary purposes.
Insurance inspections protect your financial interests by ensuring your coverage remains valid.
LOLER examinations protect your people and your business by ensuring equipment safety and legal compliance.
Ignoring either can lead to serious consequences, including accidents, legal penalties, and financial losses. By understanding and respecting the difference, you can create a safer workplace and a more resilient business.
Taking the Next Step
If you’re responsible for lifting machinery in your business, make sure you have a clear plan for both insurance inspections and LOLER thorough examinations. Regular, professional inspections are not just a legal obligation - they are an investment in safety and peace of mind.
For expert help, consider working with specialists who know the Midlands and wider UK areas well. They can guide you through the process, handle inspections efficiently, and help you stay compliant without the stress.
Remember, safety and compliance are ongoing commitments. Stay proactive, stay informed, and keep your equipment in the best possible condition.
By understanding the difference between insurance inspections and LOLER thorough examinations, you’re better equipped to protect your business, your employees, and your equipment. Don’t wait for an accident or a compliance issue to take action. Start today, and keep your lifting machinery safe and reliable for years to come.
FAQs
Is an insurance inspection the same as a LOLER thorough examination?
It depends what kind it is. A risk survey, done so the insurer can decide whether to cover you, isn’t a LOLER examination. But many engineering policies include the LOLER thorough examination itself, carried out by the insurer’s engineer surveyor, and that does count.
Is an insurance inspection a legal requirement?
The risk survey isn’t. It’s a condition of your cover, not the law. The LOLER thorough examination is a legal requirement under Regulation 9 of LOLER 1998, whether your insurer’s surveyor or an independent examiner carries it out.
How can I tell if my insurance inspection report counts as a LOLER examination?
Look for the words “report of thorough examination” and a reference to LOLER 1998. A proper report also states the safe working load, any defects, the date by which the next examination is due, and the examiner’s name and qualifications.
Can I use an independent examiner if my insurance policy includes inspections?
Yes. LOLER says the examination has to be done by a competent person, not by your insurer. Ask whether the inspection part of the policy can be dropped on its own, and whether your insurer wants copies of the new reports.
Does my insurer need to see my LOLER reports?
Often, yes. Many engineering and liability policies expect statutory examinations to be up to date, and an insurer may ask for proof after a claim. If an independent examiner does your examinations, send your insurer a copy of each report.
How often do insurance inspections happen?
A risk survey happens when the insurer decides, often at the start of cover or at renewal. If your policy includes LOLER examinations, they follow the legal intervals: at least every 6 months for equipment that lifts people and for lifting accessories, and 12 months for other lifting equipment.
What happens if equipment fails an insurance inspection?
After a risk survey, the insurer may raise your premium, add conditions or refuse cover. A failed LOLER examination is more immediate. A dangerous defect means the equipment can’t be used until it’s fixed, and serious risks are reported to the enforcing authority.
Who can carry out a LOLER thorough examination?
A competent person with the practical and theoretical knowledge to find defects and judge how serious they are. HSE also says they should be independent and impartial, so not the person who maintains the equipment. That can be an insurer’s surveyor or an independent examiner like PULO Compliance.


Comments